Starvard University · Budgeting 101
Tell your money where to go. A budget is not a punishment; it is a plan that makes sure your money serves your life.
The whole course in brief
The twelve lessons
Lesson 1
Most people hear "budget" and picture deprivation: no lattes, no fun, a spreadsheet of shame. Flip it. A budget is permission to spend on what you love, because the important stuff is already handled. It is the difference between wondering where your money went and telling it where to go.
The research is consistent: people who budget save more, stress less about money, and argue less with partners about spending. Not because budgeting is magic, but because attention changes behavior. What gets measured gets managed, and what gets planned gets funded.
This course will not ask you to stop enjoying money. It will ask you to decide, in advance and on purpose, what your money is for. That single shift, from reactive spending to intentional spending, is worth more than any single tip in the next eleven lessons.
Lesson 2
Before you build a budget, gather data. For one full month, record every dollar you spend, no judgment, no changes yet. Use an app that syncs to your accounts, a notes file, or pen and paper. The method does not matter; the completeness does.
This month will surprise you. Almost everyone discovers two or three spending leaks they had no idea existed: the subscription graveyard, the daily convenience spending, the category that is triple what they guessed. These surprises are the raw material of a good budget.
Do not try to fix anything during the tracking month. You are a scientist observing, not a judge sentencing. The moment tracking becomes about guilt, you will stop doing it. Curiosity now, decisions later.
Lesson 3
The simplest budget that actually works: 50 percent of take-home pay to needs (housing, food, transport, minimum debt payments), 30 percent to wants (dining, hobbies, travel), and 20 percent to savings and extra debt payoff. Three buckets, no spreadsheet gymnastics.
The power is in the guardrails. When housing creeps toward 40 percent, the budget tells you something has to give, before the credit card tells you. When wants hit their 30 percent cap, you choose deliberately instead of drifting. Constraints create clarity.
High-cost cities break the 50 percent needs cap for many people, and that is fine; adjust to 60/20/20 or whatever reflects reality. The percentages are a starting template, not a law. The principle is fixed proportions for savings first, lifestyle second.
Lesson 4
Zero-based budgeting gives every single dollar a job before the month begins. Income minus all assignments equals zero. Not zero in your account, zero unassigned. Every dollar is earmarked: rent, groceries, savings, fun money, all of it, on purpose.
This method shines for people who want total control or who are digging out of debt. It forces the trade-offs into the open: the new jacket means less dining out, stated explicitly. Nothing hides in the "miscellaneous" fog because there is no miscellaneous.
The cost is effort: it takes 30 to 60 minutes to build each month, plus a few minutes weekly to track. Apps make it nearly painless now. If that sounds like too much, the 50/30/20 method from lesson three gets you 80 percent of the benefit for 20 percent of the work.
Lesson 5
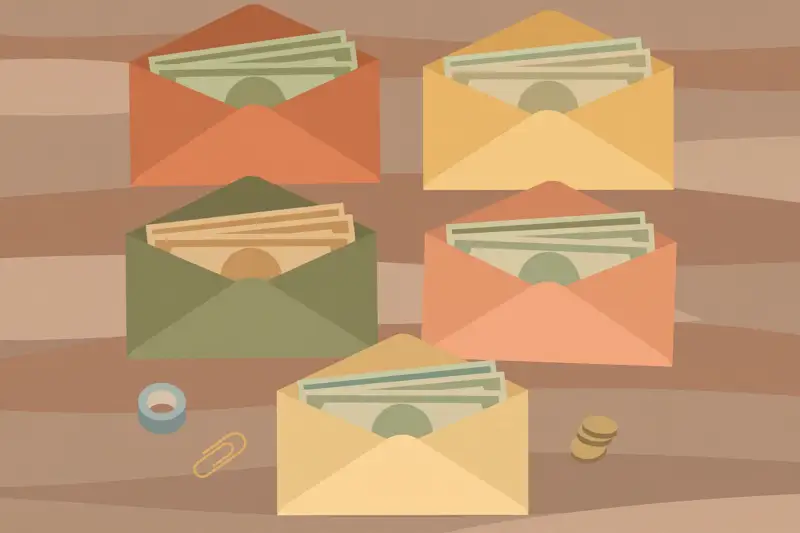
The envelope system is budgeting you can touch. Put cash in labeled envelopes for variable spending: groceries, dining, fun, gas. When an envelope is empty, that category is done for the month. The physical limit does what willpower cannot.
It works because spending cash hurts more than swiping, a well-documented psychological effect. Digital versions exist in budgeting apps with virtual envelopes, and they capture most of the benefit. But if overspending is your core struggle, try real cash envelopes for one month; the lesson is unforgettable.
Use envelopes only for variable spending, not fixed bills. Rent and utilities do not need envelopes; groceries and entertainment do. Five or six envelopes cover most households. The system is old, simple, and brutally effective.
Lesson 6
Cutting spending fails when it targets what you love. The trick is to cut ruthlessly what you do not care about and protect what you do. Audit your tracking data for spending that bought no joy: forgotten subscriptions, convenience fees, duplicate services, the premium tier you never use.
The big three expenses, housing, transport, and food, dominate every budget. One smart move here beats fifty tiny ones. Refinancing, a cheaper apartment at lease renewal, or cooking four more dinners a week each move the needle more than a year of skipped lattes.
Negotiate the recurring bills: internet, phone, insurance. A twenty-minute call often cuts 10 to 20 percent. And institute a 48-hour rule for non-essential purchases over a set amount; most "wants" evaporate in two days, and the ones that survive are worth buying guilt-free.
Lesson 7
Freelancers and gig workers cannot budget a fixed paycheck, so budget a fixed salary instead. In good months, sweep the surplus into a holding account. In lean months, pay yourself the same salary from the holding account. You become your own steady employer.
Base the salary on your worst reasonable month, not your average. Prioritize in this order when money arrives: taxes owed, essential bills, savings target, then lifestyle. The holding account needs one to two months of expenses before it feels stable; build it as the first goal.
Quarterly estimated taxes deserve their own sub-account, untouchable for any other purpose. Freelancers who mix tax money with spending money learn this lesson exactly once, usually in April.
Lesson 8
Sinking funds turn lumpy expenses into smooth monthly ones. Car insurance due twice a year? Divide by six and save monthly. Holiday gifts, car repairs, annual subscriptions, vacations: each gets its own little fund, fed automatically every month.
The magic is that irregular bills stop being emergencies. When the $800 car repair arrives, the fund covers it and the budget does not flinch. Most "unexpected" expenses are actually perfectly predictable; they just do not arrive monthly.
Start with three funds: car, gifts and holidays, and home or personal maintenance. Add more as you spot patterns in your tracking data. A high-yield savings account with labeled sub-accounts or buckets is the ideal home for them.
Lesson 9
Money fights are rarely about money; they are about unspoken expectations. The fix is a regular money date: twenty minutes, monthly, reviewing spending and plans together, with snacks and zero blame. The agenda is the future, not an audit of the past.
Combine forces on shared goals while preserving autonomy. Many happy couples run joint accounts for shared bills and savings plus individual "fun money" accounts, no questions asked. The personal allowance ends 90 percent of spending arguments before they start.
Agree on a threshold above which purchases get a quick heads-up, maybe $100 or $200. Below it, total freedom. This single rule balances partnership with independence, and it works because it was agreed, not imposed.
Lesson 10
Every budget breaks. The car dies, the medical bill arrives, the month just gets away from you. The budget did not fail; reality happened. The correct response is to adjust the budget, not abandon it. A budget is a tool, not a moral contract.
Do a five-minute reset: what blew up, by how much, and which categories absorb it this month? Move money between envelopes openly rather than pretending the overspend did not happen. One bad month is data; quitting is the only real failure.
If the same category breaks three months running, the budget is wrong, not you. Raise that category's allocation and cut elsewhere, or accept that your plan needs restructuring. Budgets serve life; life does not serve budgets.
Lesson 11
Willpower is a terrible financial plan. Automation is a great one. On payday, money should move on its own: to savings, to investments, to sinking funds, to bill pay. What never reaches your checking account never gets spent.
The automation stack: direct deposit split (part to savings), automatic transfers to investment accounts, autopay for every fixed bill, and automatic sinking fund contributions. Set calendar reminders to review quarterly, but let the system run itself monthly.
Start with one automation this week, the savings transfer. Even $50 per payday, automatic, beats $500 intended but never moved. Add one automation per month until the important money moves without you. The best budget is the one you do not have to remember.
Lesson 12
Once a year, give your money a full checkup. Pull the year's spending totals by category and compare to your plan. Celebrate what worked. Notice what drifted. Update the budget for the year ahead: new income, new goals, new costs.
The review agenda: net worth (up is good), savings rate (aim higher yearly), debt balances (down is good), subscription audit (cancel the forgotten), insurance shopping (biennial), and goal progress (the trip, the house, the freedom fund). One focused hour, once a year.
Then set one money goal for the coming year, just one. Raise the savings rate a point. Kill the last debt. Fund the trip in cash. A single clear target focuses twelve months of small decisions, and next year's review starts with a win.
Graduation
You tracked, you chose a method, you automated the important parts, and you know what to do when life breaks the plan. Money is now a tool you direct, not a mystery that happens to you. Every dollar has a job, and the jobs serve your life.
Keep learning
This course is part of Starvard University, striving for greatness.
A note on accuracy: Much of what you read at Starvard was created with help from AI agents, working alongside people. We check what we can, but we cannot guarantee that everything here is true, current, or complete. If something really matters, your health, your money, a grade, a job, please verify it with a trusted source before you rely on it.